The Dry Powder Deadline: Private Equity's $3.7 Trillion Wait
The industry is sitting on $3.7 trillion of committed capital — and it's aging. Forty percent has been ready for two years, the 2022-23 vintages are hitting their deployment deadlines, and zombie funds have risen sixfold. What happens when the vault must buy something.
By MyAudioBooks.ai ·
Listen free: The Dry Powder Deadline: Private Equity's $3.7 Trillion Wait
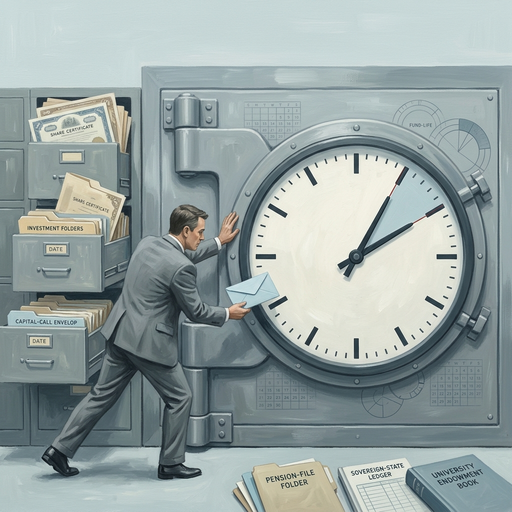
There is a vault on the balance sheets of the world's private-equity firms, and it currently holds three point seven trillion dollars of other people's money. That is the industry's dry powder — capital committed by pension funds, endowments, and sovereign wealth funds, drawn down and ready to invest — and it is roughly double what it was in twenty nineteen. The vault's existence is not news. What is news, this year, is what is happening to the contents: they are getting old. More than forty percent of the capital sitting ready for deployment has been ready for more than two years. The majority of the trillion-three-hundred-billion in buyout dry powder belongs to the fund vintages of twenty twenty-two and twenty twenty-three — the cohort raised at the very top of the market, just before the exits froze. And at the far end of the age spectrum, the industry's own data now counts a sixfold rise in zombie funds — vehicles more than ten years old, long past their intended lives, still holding more than a trillion dollars of companies nobody has managed to sell.
Every fund ever raised carries a clock, and the clock is what turns a pile of aging capital from an asset into a problem. The clock is called the investment period: the span, typically five years, during which the manager is entitled to deploy the fund's committed capital into new deals. When the investment period ends, the rules change — the manager may only follow on in existing holdings, and every extension of the clock must be negotiated with the investors, usually for a price. The problem confronting the industry in twenty twenty-six is arithmetic: the funds raised at the top in twenty twenty-two are now entering the final stretch of their deployment windows with the exit market still logjammed, the entry prices of anything good still high, and three point seven trillion dollars of pressure building behind the same narrow door. Capital under deadline pressure does not sit quietly. It deploys. And capital that deploys under pressure, at the wrong point in the cycle, is how the next vintage of write-downs gets purchased.
This is the story of the aging vault — what the dry-powder mountain is, why its age profile matters more than its size, and what the industry's own adaptation machinery says about the pressure it is under.
At My Audio Books dot A I, you can create your own audiobooks from prompts, turn your documents into audio, all with one subscription, and store your items in your own personal library.
First, the mechanics of commitment, because the dry-powder number means less than people think without them. When an investor commits to a private-equity fund, the money does not move. The investor signs a pledge, and the manager draws the capital down over the investment period as deals are found — which means dry powder is not a pile of cash in a bank but a pile of promises with expiration mechanics attached. The promises are irrevocable: miss a capital call — the manager's formal demand for a slice of your commitment, typically with ten days to pay — and the investor faces penalties up to forfeiture of their entire stake, accumulated returns and all. This is not a theoretical edge case. In the depths of two thousand eight, a handful of high-profile investors missed calls and lost everything they had built in those funds; the memory shapes behavior to this day, and it is part of why the mountain keeps growing even when investors privately wish it would stop. You cannot un-promise. You can only sell the promise to someone else — at a discount, in the secondaries market this channel covered last week — or fund it. And the promises are time-boxed by the fund documents: the five-year deployment window, the ten-year fund life, and the additional year or two the manager can request from the investors when time runs short. Every one of those mechanics is now under strain at once, because the industry built the current mountain during the easiest fundraising years in its history. In twenty twenty-one and twenty twenty-two, investors committed record sums to private equity at record valuations, and the managers did what managers do with record commitments: they raised the biggest funds ever seen. The fundraising numbers from those years read, in retrospect, like a fever chart: flagship buyout funds closing at twenty, twenty-five, thirty billion dollars each; first-time funds raising billions on a pitch deck and a team photo; sovereign wealth funds and public pensions competing for allocations as if the window were closing. The total committed across the industry in those two years exceeded a trillion dollars annually — the fastest capital formation in the history of the asset class, assembled at the highest prices the companies being bought had ever commanded. Every dollar of it came with the same clock attached. Then the rate shock hit, the exit market froze, and the industry's normal metabolism — sell the old, buy the new, return the cash, raise the next fund — seized. The selling stopped first. The buying slowed second. The commitments, made in the fat years, did not stop at all. They sat in the vault, aging.
The age profile is the finding that matters, so it is worth reading carefully. The McKinsey breakdown of the mountain shows more than forty percent of deployment-ready capital has now been available for over two years — capital committed in the expectation of being put to work within months, sitting idle through its second birthday. The Bain analysis shows the buyout portion is concentrated in the twenty twenty-two and twenty twenty-three vintages — a vintage, in the industry's vocabulary, being simply the year a fund was raised, used the way wine people use it, because funds are judged by the year of their birth and the prices that year imposed. Those two vintages must deploy soonest, or start asking their investors for more time, a conversation no manager enjoys because it concedes the clock won.
And at the far end of the age spectrum, the Preqin data shows the consequence at the fund level: a sixfold rise in zombie funds — a zombie fund being the industry's own name for a vehicle that has blown past ten years without winding down, still holding unrealized assets now topping a trillion dollars, still drawing fees on marks that have not been tested in years. The zombie funds are the oldest layer of the same sediment: funds from an earlier cycle that never cleared. This channel documented the exit side of that logjam last week — the three point eight trillion dollars of unsold companies and the continuation-fund boom built to refinance them. The dry-powder mountain is the same logjam seen from the other side: not the assets that cannot leave, but the capital that cannot land.
At My Audio Books dot A I, you can listen to this story and thousands of others that explore the hidden science and mechanics behind the headlines.
Who owns the mountain? The composition matters, because the pressure transmits through it. The largest blocks of committed capital come from public pension funds — the retirement systems of teachers, firefighters, and state workers, for whom private equity has become the single largest alternative allocation — followed by sovereign wealth funds, university endowments, insurance balance sheets, and, increasingly, the private wealth of individuals newly admitted to the asset class through the evergreen vehicles this channel described in the private-credit story. Each owner has its own liquidity metabolism. The pension needs distributions to pay benefits and to fund its next commitments. The sovereign fund can wait decades but answers to a ministry that reads quarterly marks. The endowment runs the pacing model this channel covered in the secondaries story, and it is already bent. The retiree in the evergreen fund has been promised quarterly liquidity. Every one of those metabolisms is now pressing on the same vault at the same time.
What does deadline pressure actually do to behavior? The honest answer is that it depends on the manager, and the industry sorts itself into three visible responses, each observable in the current data. The first response is discipline: the best managers simply let the clock run and ask for the extension, accepting the embarrassment, because deploying bad capital is worse than admitting the calendar beat you. The second is drift, and it is already visible in the deal data: capital edges down-market into smaller deals where competition is thinner, into adjacent strategies the fund was not raised for, and above all into structured equity — the preferred-stock-like instruments that offer a contracted return with an equity wrapper, deployed at prices that look disciplined on a spreadsheet while quietly re-rating the same assets the fund could not buy outright. Structured equity is the pressure valve of choice this cycle: it lets a manager say the capital is deployed, the return is contracted, and the discipline held — while the instrument's whole purpose is to make a full-price purchase feel like a conservative one. The parking lot is well lit and carefully marked. It is still a parking lot. The third is the one the industry's veterans watch with the most concern, and it rhymes with everything else this cycle has produced: deployment into the consolidation machinery itself — the mega-buyouts, the consortium deals, the continuation vehicles — where size substitutes for price discipline and the fee structures reward activity over outcome. When a five-billion-dollar fund has eighteen months of investment period left, a forty-billion-dollar consortium buyout starts to look less like a strategy and more like a solution to a calendar problem.
It is worth doing the deployment arithmetic out loud, because the scale of the required landing is the part of the story the headlines skip. For the mountain to drain on schedule, the industry would need to deploy on the order of a trillion dollars a year, every year, for the next several years — at a time when its own megadeal-driven rebound last year, the strongest in the recovery, produced nine hundred billion of buyout deal value across the entire industry, and much of that was funded not from the dry-powder vaults but by sovereign wealth and corporate co-investors writing separate checks alongside. In other words: even the good years no longer dent the pile. The vault grows faster than the industry's best deployment year can empty it, and it has been growing faster for three consecutive years. That is not a cyclical backlog anymore. It is a structural change in the industry's ratio of commitments to opportunities — more promises than there are companies worth buying at prices worth paying — and structural changes do not unwind in a quarter.
The strongest case that the mountain is an asset rather than a liability deserves a full hearing, because it is the case the industry itself makes, and it is not nothing. Dry powder is optionality: three point seven trillion dollars of committed capital means the industry can move with overwhelming force when the market finally clears, buying the recovery at distressed prices the way it did after two thousand eight — the vintage funds raised into downturns are historically the best-performing funds the industry has ever produced, and the twenty twenty-four through twenty twenty-six vintages may join that list precisely because of the deployment freeze. The age problem, in this reading, is temporary by construction: exits are already rebounding on megadeal strength, the rate environment is normalizing, and a year of open exits would let the vault drain into genuinely attractive prices. The rise of the ten-year-old vehicles, the bulls note, is a stock measure from a frozen moment, not a flow of new failures. And the extension mechanics exist precisely for this situation — investors grant them routinely when the alternative is forced deployment, because investors understand calendars too. On this reading, the mountain is the industry's dry reservoir, not its flood risk, and the current discipline is evidence the system works.
And the strongest case against is written in the part of the data the bull case skips: the vintage mathematics. The funds under the most pressure are not the new vintages that will benefit from future distress prices — they are the twenty twenty-two and twenty twenty-three funds, which must deploy now, into today's prices, with their investment periods expiring into the teeth of the logjam. The historical pattern the bulls invoke — downturn vintages outperform — has a mirror image, and the industry knows it in its bones because it lived it: the funds raised in two thousand six and two thousand seven, at the peak before the financial crisis, deployed enormous sums into peak-priced mega-buyouts in the final stretch of their windows, and spent the following decade as the industry's cautionary examples, their returns rescued only by the longest bull market in history. The lesson that cycle burned in is precisely the one the current moment tests: it is not the size of the capital that determines the outcome, it is the prices paid in the window the calendar forces. Peak-vintage funds forced to deploy at the end of their windows have historically produced the industry's worst returns, because pressure deployment is how disciplined capital becomes undisciplined. The fee structure sharpens the point: management fees run on committed capital regardless of deployment, so the mountain pays the managers handsomely whether or not it ever lands — the industry's incentive to deploy carefully is real, but its incentive to deploy eventually is absolute. And the zombie funds are the proof of what happens when the whole apparatus fails: not collapse, but permanent fee-supported limbo, a trillion dollars strong and growing sixfold, in which the only party reliably paid is the manager.
Three developments would disprove or confirm which reading the next two years ratify, and each is observable. First, the time-buying wave: watch the rate at which the funds raised at the peak request more time on their deployment clocks through this year and next — a high rate of such requests is the discipline reading winning, while a low rate paired with rising deal volume means pressure deployment is underway. Second, the pricing of new deals: if entry multiples for new buyouts fall as the dry powder deploys, the market is clearing rationally; if multiples hold or rise while three point seven trillion lands, the pressure is inflating prices at the exact moment discipline is most needed. Third, the zombie-fund stock: whether the trillion-plus dollars trapped in ten-year-old vehicles begins to wind down through real exits, or continues to compound into the secondaries and continuation machinery, will show whether the sediment clears or hardens.
One more uncomfortable fact belongs in the record before the verdicts, because it explains why the mountain's critics inside the industry stay anonymous: the mountain pays. Management fees across the industry run, by long-standing convention, on the order of one and a half to two percent of committed capital per year during the investment window, which means the three point seven trillion dollars of dry powder throws off something like fifty to seventy billion dollars a year in fees — before a single company is bought, before a single dollar of profit is proven, whether or not the capital ever lands. The fee is not a scandal; it is the contract, signed by sophisticated investors who knew the terms. But it changes the psychology of the deadline: the party with the least financial urgency to deploy is the party holding the pen, and the parties with the most urgency are the ones who promised to pay. When you read that a fund is taking its time, it is worth remembering whose time is being paid for.
It is worth saying what this article has not claimed. It has not claimed the dry powder is wasted or stolen; it is committed capital working exactly as the fund documents provide, and the fees on it are contractual. It has not claimed all managers deploy under pressure; the discipline response exists, is common among the best firms, and is described in this article by name. It has not claimed the mountain guarantees bad outcomes; the optionality case is stated at full strength and may prove right. And it has not claimed the logjam is permanent; the same data that shows the freeze shows the first thaw, and the industry's own projections have fundraising re-accelerating from twenty twenty-seven. The claim here is narrower and more mechanical: three point seven trillion dollars of time-boxed promises is not a neutral fact, because time-boxed capital deploys eventually, and the window in which it deploys is being chosen by the calendar rather than the opportunity.
Which returns to the vault, and the promises inside it, and the quiet fact that a promise with an expiration date is a different thing from money. The pension teacher in Ohio and the sovereign fund in Singapore made those promises in the fat years, expecting the old rhythm — five years in, ten years out, cash on schedule. The mountain says the rhythm broke. The zombie funds say what happens when it breaks for a decade. And the investment-period clocks now ticking on the twenty twenty-two vintage say the industry is about to find out what three point seven trillion dollars of deadline pressure buys in a market that has not finished clearing. The last time this much committed capital met this much frozen inventory, the industry's own report called the result a record logjam. What it calls the next phase will depend on what the vault buys — and the vault, remember, must buy something. That is the whole point of a clock.
At My Audio Books dot A I, you can create fiction, non-fiction, and turn your documents into audio, all stored in one place with a single subscription — plus get instant access to thousands of audiobooks and deep-dive investigations. Learn more today at My Audio Books dot A I.