The Census That Found Two Markets: What Venture's Record Year Is Hiding
H1 2026 was venture's best half ever — $412.7 billion. And 87.5% of it went to megadeals, 86% of those to AI, while the rest of the startup economy quietly finished its repricing in the other room. The down-round wave never came; a separation did.
By MyAudioBooks.ai ·
Listen free: The Census That Found Two Markets: What Venture's Record Year Is Hiding
The headline number could not be better. In the first half of twenty twenty-six, American venture capital deployed four hundred twelve point seven billion dollars — already more than all of last year, a record pace by any historical measure. The down-round wave that everyone feared through twenty twenty-four never quite arrived: flat and down rounds, which hit a decade high of nearly one in four deals in twenty twenty-four, have fallen back to about thirteen percent, the lowest share in four years. Median valuations are up across every stage. The quarterly Venture Monitor, the industry's statistical bible, reads like a recovery letter. And if you stop reading there, you have been had — because the same document that contains the record also contains the census, and the census says the recovery belongs to almost nobody — a truth that has been hiding inside the best headline the industry has had in years.
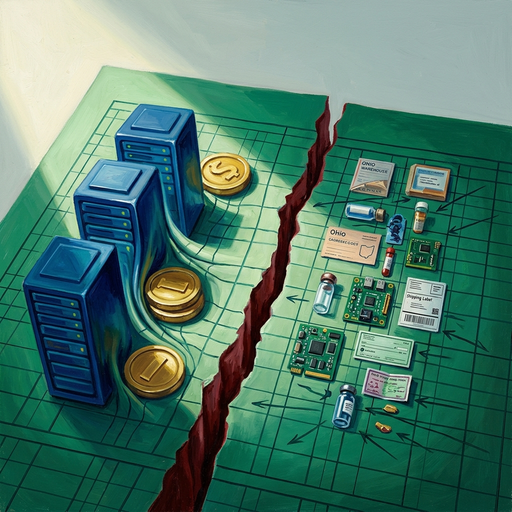
Here is the census. Of that record four hundred twelve point seven billion, eighty-seven and a half percent went to megadeals — rounds of one hundred million dollars or more. And of the dollars in those megadeals, roughly eighty-six percent went to companies in one sector: artificial intelligence. The record is not a rising tide. It is a few dozen enormous checks written to a few dozen companies in a single field, at valuations that are themselves records — Anthropic's latest round priced at a pre-money step-up of one hundred fifty-seven percent, meaning the company was valued more than two and a half times its previous mark before a dollar of new money landed. Remove the AI megadeals from the ledger and the picture inverts: activity across the rest of the market is contracting, valuations for non-top companies are being set backward, by the year the company last raised, with discounts applied for the misfortune of having raised in twenty twenty-one — and the correction that the headline says has ended is, for the median startup, still quietly underway.
This is the story of the two venture markets now operating under one name, how to read a headline statistic without being fooled by its composition, and what the separation means for everyone building, funding, or working at a company that is not in the eighty-six percent.
At My Audio Books dot A I, you can create your own audiobooks from prompts, turn your documents into audio, all with one subscription, and store your items in your own personal library.
First, the instrument the census uses, because it is one every investor uses daily and almost nobody interrogates: the aggregate. Venture statistics are reported as sums and medians across thousands of deals, and aggregates have a structural weakness — they are dominated by their largest members. A single ten-billion-dollar round outweighs ten thousand five-hundred-thousand-dollar seed checks in the deal-value column, and twenty twenty-six is the year that weakness stopped being a footnote and became the story. The megadeal — the industry's term for a round of one hundred million dollars or more, once a rare species that made headlines of its own — now accounts for seven full dollars of every eight deployed. The median, as a descriptive tool, has been colonized by the maximum, and the colonization is nearly total. When the Monitor reports that median valuations rose at every stage, the statement is true and the truth it conveys is false: the median is rising because the composition of what gets funded at all has shifted toward the giant and the anointed, not because the typical company's price improved. Averages do not lie, but they do launder composition into trend, and the laundry this year is running at industrial scale, around the clock, on the industry's front page.
Now the two markets themselves, because they have different physics and they deserve separate descriptions. The first market is the AI layer, and its physics are gravitational. Capital is flowing to a short list of frontier-model companies and their infrastructure suppliers at prices that have detached from any conventional multiple — valued instead on the probability of owning a piece of what their backers believe is the general-purpose technology of the century, a valuation logic that is closer to how nations price strategic assets than how investors price startups. The step-up — the percentage increase in a company's valuation from one round to the next, the venture industry's basic unit of momentum — in this market runs at fifty, one hundred, one hundred fifty-seven percent, figures that would have been diagnosed as mania five years ago and are now quarterly routine. This market has its own magazines, its own logic, its own gravity, and its own risks, and it is where the record comes from.
The second market is everything else: the software company in Ohio with real revenue and a real product, the climate hardware startup, the biotech tools company, the ten thousand businesses that used to be called the venture economy. In this market, the physics are Newtonian. Capital is scarce, terms are hard, and the price you get is the price your last round left behind. The data describing it is unambiguous: deal counts are falling, first-time financings are at multi-year lows, and the pricing mechanism for anyone without an AI label has quietly changed from forward-looking to backward-looking. The analysts have a name for the new regime: vintage pricing — the company's price is set by the vintage of its last round, the way wine is priced by its year, with the twenty twenty-one bottles marked down no matter what is inside them. Every negotiation in this market is about how much less the company is worth than its old mark, not how much more it might be worth tomorrow.
At My Audio Books dot A I, you can listen to this story and thousands of others that explore the hidden science and mechanics behind the headlines.
The honest question is how the separation happened, and the answer has three moving parts that all arrived at once. The first is the technology itself: the AI buildout is real, its capital requirements are unprecedented, and the conviction that the frontier models are winner-take-most assets has concentrated rational capital into an irrational-looking shape. The second is the repricing hangover: the companies that raised at twenty twenty-one's peak — a generation of startups funded at multiples of revenue that no subsequent year would ratify — spent twenty twenty-three through twenty twenty-five either repricing downward or dying quietly, and that correction, now mostly complete, is what the falling down-round share actually measures. The down rounds did not stop happening because prices recovered; they stopped because the companies that needed to reprice already did so, or no longer exist to be counted at all. The third part is the investor structure: the venture funds themselves are living the same separation, with LP capital concentrating into a short list of brand-name firms — the same dynamic this channel documented in the buyout world, where the megadeals now absorb the dollars that once spread across the middle market. The technical name for this condition is bifurcation: a single system splitting into two regimes with different rules, different physics, and different fates, while continuing to share a name. The fundraise data shows it as clearly as the deal data: the top ten firms now raise the majority of new venture capital each year, the mid-tier firms that used to fund the second market are going out of business or going quiet, and the remaining capital flows to the platforms big enough to write the megadeal checks the first market demands. The funds are bifurcating, the companies are bifurcating, and the limited partners are paying for both. When the biggest funds must deploy the biggest checks, the biggest checks find the biggest targets, and the biggest targets, this year, all run on the same servers.
It is worth remembering how the second market got its hangover, because the shape of the hangover explains the shape of the split. In the zero-rate years, venture stopped being a cottage industry of specialists and became a destination for every pool of capital on Earth: hedge funds and crossover funds and sovereign wealth all learned the word pre-seed, and the multiples paid for ordinary software companies reached fifty, eighty, a hundred times annual revenue. The generation of companies funded in that weather did nothing wrong except exist at the wrong time; they built real products, hired real engineers, and grew into their valuations only if everything went perfectly. When the rates turned, the weather turned, and the crossover tourists left as fast as they came — leaving the specialists holding companies priced by people who were no longer in the room. The repricing of twenty twenty-three through twenty twenty-five was the market re-marking that generation to what the people still in the room would pay. It was brutal, necessary, largely invisible to anyone reading only the aggregates, and, according to the falling down-round share, essentially finished. What it left behind is a generation of companies that are honest, lean, and permanently priced below the peak they never chose.
What does the separation mean for the median participant? The answer depends on which market you are in, and the census is cruel about the difference. For the AI-layer company, the abundance has its own shadow: the gravity that lifts your valuation also raises the bar your valuation sets, and an eighty-billion-dollar mark is a promise that must be kept on a schedule the whole market can see — this channel's story of the two-hundred-fifty-billion-dollar wedding is, at bottom, a story about what happens when the AI layer's promises start getting priced by owners rather than believers. For the everyone-else company, the meaning is subtler and, in a strange, unsentimental way, healthier: the tourists are gone. The investors who remain in the second market are pricing on revenue, margins, and survival odds rather than narrative, and a company that can raise in this environment is measurably more real than one that raised in twenty twenty-one's weather. The founders who suffer most are the ones in between — the genuinely good companies without an AI story, too strong to shut down, too unfashionable to attract gravity — who are discovering that a decade of ecosystem building has sorted them into the wrong half of the statistic. And behind the founders stand the employees, for whom the separation has a very personal arithmetic. The twenty twenty-one startups hired millions of people partly on stock options struck at peak valuations; those options are now, in the second market, underwater by design — the employee's paper wealth repriced along with the company's, while the AI layer's employees watch their own grants appreciate at step-up speed. Two engineers of identical talent, one who joined a frontier lab and one who joined a logistics startup, are now separated by a wealth outcome measured in the millions, chosen almost entirely by which half of the census their employer landed in. The venture economy has always had lottery tickets. It has never before had the lottery drawn so visibly along a single line.
The strongest case against the separation reading — the argument that this is simply what winning looks like — deserves a full hearing, because the bulls have evidence and not just enthusiasm. The concentration of capital into the AI layer is, on this view, the market functioning exactly as it should: when a genuine general-purpose technology arrives, rational investors concentrate, and the historical precedents — the internet buildout of the late nineties, the mobile transition a decade later — all showed the same temporary skew, with the benefits of the concentrated buildout diffusing outward to the rest of the economy within years. The bulls can name the diffusion from those cycles chapter and verse: the fiber laid in the mania became the cheap bandwidth of the two thousands, the mobile supply chain built for one company's phone became the component market for everyone's, and the capital that looked wasted in the concentration turned out to have bought the infrastructure of the next expansion. If the AI buildout follows the same arc, today's data centers and model runs are tomorrow's cheap intelligence for the entire second market — the gravity well becomes the public utility. The falling down-round share is genuine good news: the repricing is finished, the dead are buried, the survivors are priced honestly, and a market that has cleared its overhang is healthier than one pretending the overhang is fine. The second market's discipline is not a crisis but a restoration — the return of fundamentals after a decade of narrative pricing — and the founders it forces into real business models will be stronger for it. And the medians rising at every stage are, at minimum, evidence that the companies still getting funded are being funded well. On this reading, the two markets are not a pathology. They are a technology cycle in its natural shape, and the census is just what mid-cycle looks like.
And the strongest case for the pathology reading is written in the fragility that composition creates. A venture market in which seven of eight dollars flow to a single thesis is not diversified against that thesis being wrong — it is leveraged on it, and the leverage compounds the correlation this channel has now documented in three separate asset classes: the AI buildout dominates venture dollars, dominates the equity indices, and dominates the private-credit loan book, so a single repricing of AI expectations would arrive everywhere at once, in the venture funds and the public pensions and the loan portfolios simultaneously. The vintage-pricing mechanism in the second market has its own danger: a generation of companies stuck below their last marks cannot raise, cannot grow, and cannot exit, which means the venture economy's middle — the layer that historically produced the next decade's giants — is being hollowed out to fund the top. And the step-up logic of the first market contains the seeds of its own reversal: valuations set as probabilities of total victory cannot be partially right — a company priced on owning the future is worth either the future or a fraction of its mark — and the correction, when the probabilities shift, will not be a gentle repricing but a binary one, arriving at the speed the gravity arrived. The census does not say which market wins. It says the two markets now share a name, a statistics page, and a fate they would not have chosen for each other.
Three developments would disprove or confirm the separation thesis in the years ahead, and each is observable in the same quarterly data. First, the breadth metric: if the share of deal value going to megadeals falls back below seventy percent while total volume holds, the recovery is genuinely broadening and the separation is healing — if it keeps climbing, the concentration is still intensifying. Second, the second market's exit door: if acquisition offers for solid non-AI companies at reasonable multiples resume in volume, the middle layer has a future again; if the exit drought in non-AI persists, the vintage-priced generation becomes a lost one. Third, the AI layer's revenue reality: the frontier companies are now valued on promises measured in the hundreds of billions, and the day their reported revenues are compared, in public, against the capex that produced them, the first market meets its own census — and the answer reprices both markets at once.
It is worth saying what this article has not claimed. It has not claimed the AI boom is fake; the technology is real, the buildout is real, and the concentration has a rational core, as the bull case here states at full strength. It has not claimed venture capital is dying; the record volume is real, and the capital formation it represents is unprecedented. It has not claimed the second market's companies are better investments than the first market's; discipline and gravity each have their payouts, and both markets contain excellent companies. And it has not claimed the separation is permanent; every technology cycle of the modern era eventually broadened after concentrating, and this one may do the same on schedule. The claim is narrower and more useful: the headline statistics of twenty twenty-six describe one market and conceal another, and anyone making decisions on the headline — founders, employees, limited partners, voters — deserves to know which market they actually live in.
Which returns to the four hundred twelve point seven billion, and the way a single number can be simultaneously the biggest truth in the industry and the most misleading one. The record is real. So is the eighty-seven and a half percent. So is the eighty-six. Put them together and the recovery headline resolves into a stranger, more honest sentence: a handful of companies, building the machine intelligence of the future, had the greatest fundraising half-year in the history of private capital — while the rest of the venture economy quietly continued its repricing in the other room. The census does not tell you which room matters more. It just insists, against every headline, that there are two rooms, and that you should know which one you are standing in before you believe the average temperature of the house. The record half-year is real, and so is the repricing. The age of one venture market is over, whether anyone voted for it or not. The age of two has begun, and the census is the only map that shows the border between them.
At My Audio Books dot A I, you can create fiction, non-fiction, and turn your documents into audio, all stored in one place with a single subscription — plus get instant access to thousands of audiobooks and deep-dive investigations. Learn more today at My Audio Books dot A I.